Most China edge-vision launches still lead with integer TOPS. Visinex did the opposite this week. Co-founder / VP 汪坚 Wang Jian told 爱集微 the chip starts from what mainstream pan-vision customers actually buy on: image quality, compute efficiency, energy, supply security, and cost* — not another “domestic general-purpose” badge. If you ship security cams, drone gimbals, action cams, or multi-cam robot heads into China OEM lines, that framing is the story: a mid-tier SKU meant to grow share after the company already sold into the mid/high band.
Who Visinex is (and what not to confuse)
Founded 2020*; founding team from HiSilicon / Qualcomm / ZTE* with phone-SoC PPA experience*. Company claims: ISO 26262 ASIL D + AEC-Q100 G2*; R&D in Shanghai / Shenzhen / Beijing / Xi’an / Nanjing*; ~50+ design-ins / 30+ volume customers*; prior VS816A >1M units in ~1 year* (head-customer volume inside ~half a year*); ¥3亿 financing earlier in 2026*; joined China RISC-V Industry Alliance (CRVIC) as a core member in Sep 2026*. Vision line framed as covering 8–32 MP edge/side parts*.
Do not confuse VS815V with the older VS815 product page on visinextek.com (Dual A55 / ~1 TOPS-class language). That page is a different SKU. Numbers below are from the 安博会 / VS815V press cycle — not that legacy sheet.
Not as a Digi-Key / Mouser board this week. VS815V is a China OEM / design-in SoC launched at 安博会. Wang’s cadence: earliest end-product volume around 2027*, matching how prior Visinex lines moved from launch to customer ships. Overseas path, if any, is partner/ODM into China-facing device lines — not a Western cloud instance or a hobby SBC you flash tonight.
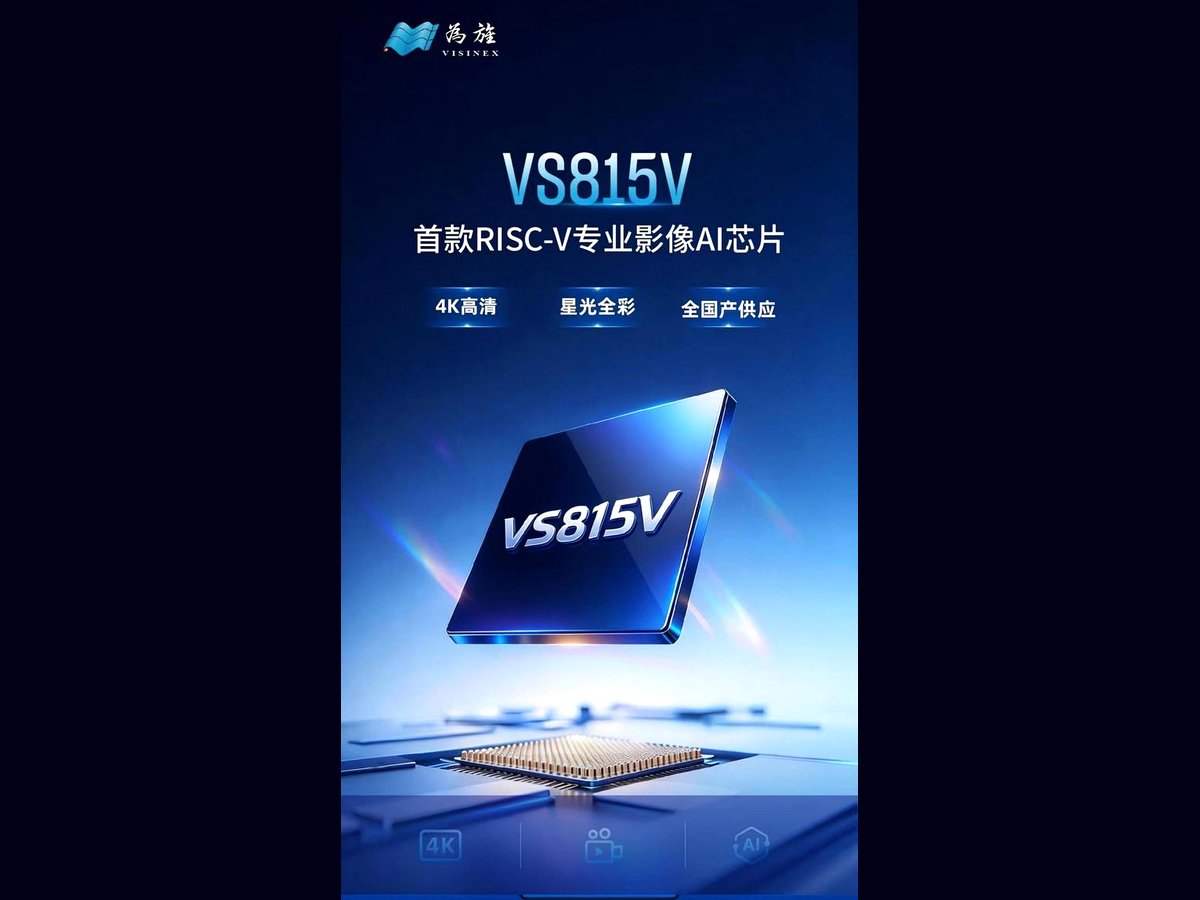
Real vertical product poster from the booth (padded to landscape for the article). Copy emphasizes RISC-V, 4K, and fully domestic supply* — vendor framing.
What VS815V actually claims*
Architecture*: first Visinex part on RISC-V for edge vision; domestic RISC-V CPU core + self-developed system MCU*. Wang’s supply-chain claim is stronger than “wafered in China on Arm IP”: process / foundry / package / critical IP all domestic*, with multiple mature domestic RISC-V IP vendors cited*. Asterisk that — it is a co-founder interview claim, not an independent BOM audit.
Differentiated hardware (same price band, more features — their words)*:
- Hardware EIS/DIS* aimed at drones & action cams (segment framed ~20% CAGR*).
- Hardware PDAF IP* — keeps 4K@30 without frame drop* vs CPU-PDAF peers that throttle under 4K@30*.
- Up to 4 MIPI sensors concurrent without an external Switch* — saves BOM and avoids time-multiplex frame-rate cuts*.
- NPU tuned for ~0.3B-param small models* for on-device natural-language interaction* (pets / simple local dialog; heavy reasoning still cloud*).
Target loads*: security / pan-vision mainstream; drones, action & livestream cams; robot vision with stereo depth and multi-cam stitch*. Prior Visinex robot cases (quadruped / humanoid) are cited as precedent*, not as VS815V reference designs you can order.
Market framing vs chip specs
Press repeats industry forecasts: China RISC-V MCU market ~¥377亿 (2025) → ~¥2194亿 (2030)*; terminal SoC RISC-V share 6.9% → 26.7% while ARM 85% → 69%*. Treat those as industry forecast slides*, not VS815V datasheet rows. Useful only as context for why a mid-tier domestic RISC-V vision part exists now — after Visinex already had volume on VS816A* and wanted a full ladder (“高端树标杆、普惠扩规模”*).
On migration: Arm-based customer algorithms need port effort*; Visinex says it offers customized secondary-development support*, or a full in-house toolchain for customers who skip rewrites*. That software tax is the real overseas evaluation item if a partner SKU ever appears — more than the RISC-V sticker.
Wang’s commercial logic is blunt: if the part only matches competitors on paper at the same ASP, customers will not switch platforms*. Switching burns supplier qualification and adaptation cost*. So VS815V’s bet is feature delta inside the mainstream price band — hardware EIS, hardware PDAF that holds 4K@30*, four concurrent MIPI lanes without a Switch*, and a small-model NPU for local NL* — then let security volume plus drone/action/livestream incremental demand pay for the ladder*. Whether that delta survives real BOM bake-offs is the engineering question; the interview is the brochure.
What changes (and what does not)
- Not Digi-Key / not ~2026 retail end products — company cadence points to ~2027* earliest finished goods*.
- Not a TOPS headline chase — positioning is mainstream 4K + feature delta (EIS, PDAF, 4×MIPI, small-model NPU)*.
- Fully domestic stack* — Wang interview; verify in design-in if supply-chain geopolitics is your constraint.
- VS816A >1M / year* and ~50+/30+ customer counts* are vendor/press — useful as traction signal, not audited revenue.
- Distinct from older VS815 web page — do not paste Dual A55 / 1 TOPS language onto VS815V.
- CRVIC membership (Sep 2026)* — ecosystem signal, not silicon proof.
Bottom line: VS815V is Visinex taking a volume swing at affordable 4K edge vision on a claimed all-domestic RISC-V stack*, after proving it can ship mid/high parts (VS816A*) and raise (¥3亿*). If you care about China security/drone/action-cam silicon menus for 2027 devices, put it on the watch list and asterisk every TOPS-adjacent boast you do not see — because this launch deliberately avoided that race.